If you are asking how much mortgage protection insurance you need in Mitchell, the short answer is the same one that applies anywhere: size it to your actual remaining loan balance, not your home’s current value or what you originally borrowed. The harder part in Mitchell specifically is that the “current value” number itself has been unusually hard to pin down this year. Mitchell’s median home listing price was $251,950 in September 2026, according to Realtor.com data hosted by the Federal Reserve Bank of St. Louis (FRED), after swinging from a 2026 high of $334,725 in March down to $222,500 in August and back up again the following month. The average 30-year fixed mortgage rate was 7.28% for the week of October 1, 2026, per Freddie Mac’s Primary Mortgage Market Survey, also via FRED. Those two figures, applied to your own loan, tell you most of what you need to know about the dollar amount at stake. What they do not tell you is whether anyone in your household could actually keep making that payment if your income stopped tomorrow, or whether the right person is even named to receive the money if something happened to you.
The short version
- Mitchell's median home listing price was $251,950 in September 2026, per Realtor.com data via FRED, down 21.3% year-over-year but up from an August 2026 low of $222,500.
- The average 30-year fixed mortgage rate was 7.28% for the week of October 1, 2026, and the 15-year average was 6.60%, both per Freddie Mac's survey via FRED.
- Only 73 active listings existed across the entire Mitchell, SD market in September 2026, per FRED. A market that small swings on a handful of sales, which is why last year's number is already unreliable.
- South Dakota's statewide house price index was up about 2.2% year-over-year as of the second quarter of 2026, per the Federal Housing Finance Agency via FRED — a far steadier trend than Mitchell's own month-to-month listing price.
- 38% of American adults, about 92 million people, say they need life insurance or need more of it, according to LIMRA's 2026 Insurance Barometer Study.
- A fixed-rate mortgage pays down slowly in its early years. On a typical Mitchell-priced loan, the large majority of the original balance is still outstanding a decade in, which matters directly for how you size decreasing-benefit coverage.
The pain: the house is the problem nobody sized
Most Mitchell homeowners can tell you their monthly payment to the dollar. Fewer can tell you what happens to that payment, and to the person stuck making it, if they are not around to make it. That is not because people do not care. It is because nobody ever sat down with them and turned “we have a mortgage on Birch Street” into an actual number that a spouse, a parent, or an adult child would need to have in hand on the worst week of their life.
The gap is not rare, and it is not a big-city problem. According to LIMRA’s 2026 Insurance Barometer Study, 38% of American adults, roughly 92 million people, say they either need life insurance or need more of it than they currently have. Mitchell, with its roughly 15,600 residents according to the U.S. Census Bureau’s 2024 population estimate, is not exempt from that math just because the Corn Palace is a smaller landmark than downtown Sioux Falls.
This is general education, not a recommendation
Nothing here tells you what coverage amount, rate class, or premium you would personally qualify for. It walks through the arithmetic and the local data so you can size your own situation, using named sources, before you talk to anyone.
Why it happens: a mortgage does not care who is left to pay it
When you and a co-borrower, typically a spouse, sign a mortgage together, you are both fully responsible for the entire balance, not half each. If one of you dies, the survivor does not inherit “their share” of the debt. They inherit all of it, on the same terms, due on the same schedule, whether or not their own income alone was ever expected to cover the payment.
If you are the sole borrower and you die, the loan does not vanish. It becomes a debt of your estate. Under federal law, 12 U.S.C. Section 1701j-3(d)(5), part of the Garn-St. Germain Depository Institutions Act of 1982, a lender generally cannot invoke a due-on-sale clause to demand immediate repayment or start foreclosure when a home passes to a relative through inheritance. The Consumer Financial Protection Bureau has directed mortgage servicers to maintain procedures for identifying and communicating with surviving family members, including, in the CFPB’s own words, “allowing heirs to continue to pay the mortgage.” That protects the right to keep the house. It does not supply the money to do it. Whoever inherits the mortgage still needs income, savings, or insurance proceeds to make the payment every month, and a house that cannot be afforded on the terms it was inherited under usually ends up sold anyway, just later and under more stress.
A few terms are worth defining before you size anything, since the products that solve this problem get confused with each other constantly:
- Mortgage protection insurance (MPI). A life insurance policy, usually decreasing-benefit term, structured around your loan’s original amount and amortization schedule. Many MPI policies are marketed by lenders or direct-response insurers and structured so proceeds address the mortgage specifically.
- Level term life insurance. A policy with a fixed death benefit for a set number of years, paid to whatever beneficiary you name, who can use the money for the mortgage, for lost income, for anything.
- Decreasing term. A term structure where the death benefit shrinks over the life of the policy, typically to mirror a loan balance declining under amortization. The premium is usually level even as the benefit declines.
- Underwriting class. The risk tier a carrier assigns after reviewing your application, which drives your premium for a given amount of coverage.
- Free-look period. The window after you receive a policy during which you can cancel it and get your premium back. In South Dakota, that window is ten days under state law, covered below.
For the deeper mechanical comparison between MPI and standalone term life, including underwriting differences and a full side-by-side cost structure, see our guide to mortgage protection insurance versus term life insurance. This piece focuses on a narrower, more local question: given what homes and loans actually cost in Mitchell right now, what number are you actually sizing coverage against?
What it costs to get wrong: the Mitchell numbers
Here is where the local data matters more than a national average, and where Mitchell looks genuinely different from a bigger South Dakota city. Mitchell’s median home listing price was $251,950 in September 2026, according to Realtor.com data hosted by FRED for the Mitchell, SD core-based statistical area, which is coextensive with Davison County. That is roughly 40% lower than Rapid City’s $417,450 median the same month, also per FRED, which is simply what a smaller regional hub costs compared to a larger one. Mitchell’s own U.S. Census Bureau figures put median household income in the city at $58,620 (with a margin of error of $7,441) and median value of owner-occupied housing units at $192,200, both from the 2020-2024 American Community Survey 5-year estimates. The gap between that $192,200 owner-occupied median value, which reflects homes already owned (often for years, at older prices), and the $251,950 current listing price is itself a reminder that what a home is worth on paper and what it costs to buy one today in Mitchell are two different numbers.
To see what today’s price means in real monthly and long-term terms, walk through an illustration. Assume a household buys near September’s median price with a 10% down payment, financing the rest at the current average 30-year rate.
| Item | Amount |
|---|---|
| Purchase price | $251,950 |
| Down payment (10%) | $25,195 |
| Loan amount financed | $226,755 |
| Monthly principal and interest | $1,551 |
Author's calculation using standard fixed-rate amortization on the loan amount and rate cited above. Excludes property tax, insurance, and any mortgage insurance premium, which would add to the actual monthly payment.
That is the payment. Here is the part that surprises most people, in Mitchell the same as anywhere else: on a fixed-rate loan, the balance you would need covered does not fall nearly as fast as the years go by.
| Years elapsed | Remaining balance | Percent paid off |
|---|---|---|
| 5 | $214,075 | 5.6% |
| 10 | $195,846 | 13.6% |
| 15 | $169,644 | 25.2% |
| 20 | $131,978 | 41.8% |
| 25 | $77,833 | 65.7% |
Author's amortization calculation on a $226,755 loan at 7.28%, the Freddie Mac average rate FRED reported for the week of October 1, 2026. Illustrative only, not a quote.
Ten years in, this illustrative household would still owe 86% of what they originally borrowed. A decreasing-term mortgage protection policy sized correctly at closing tracks that curve automatically. A level term policy does not shrink at all, which is a feature if you want flexibility and a mismatch if you specifically wanted the benefit to match the loan exactly. Either way, “we’ve had the house ten years, it’s mostly paid off” is, for most fixed-rate buyers, simply not true yet, and sizing coverage on that assumption leaves a real gap.
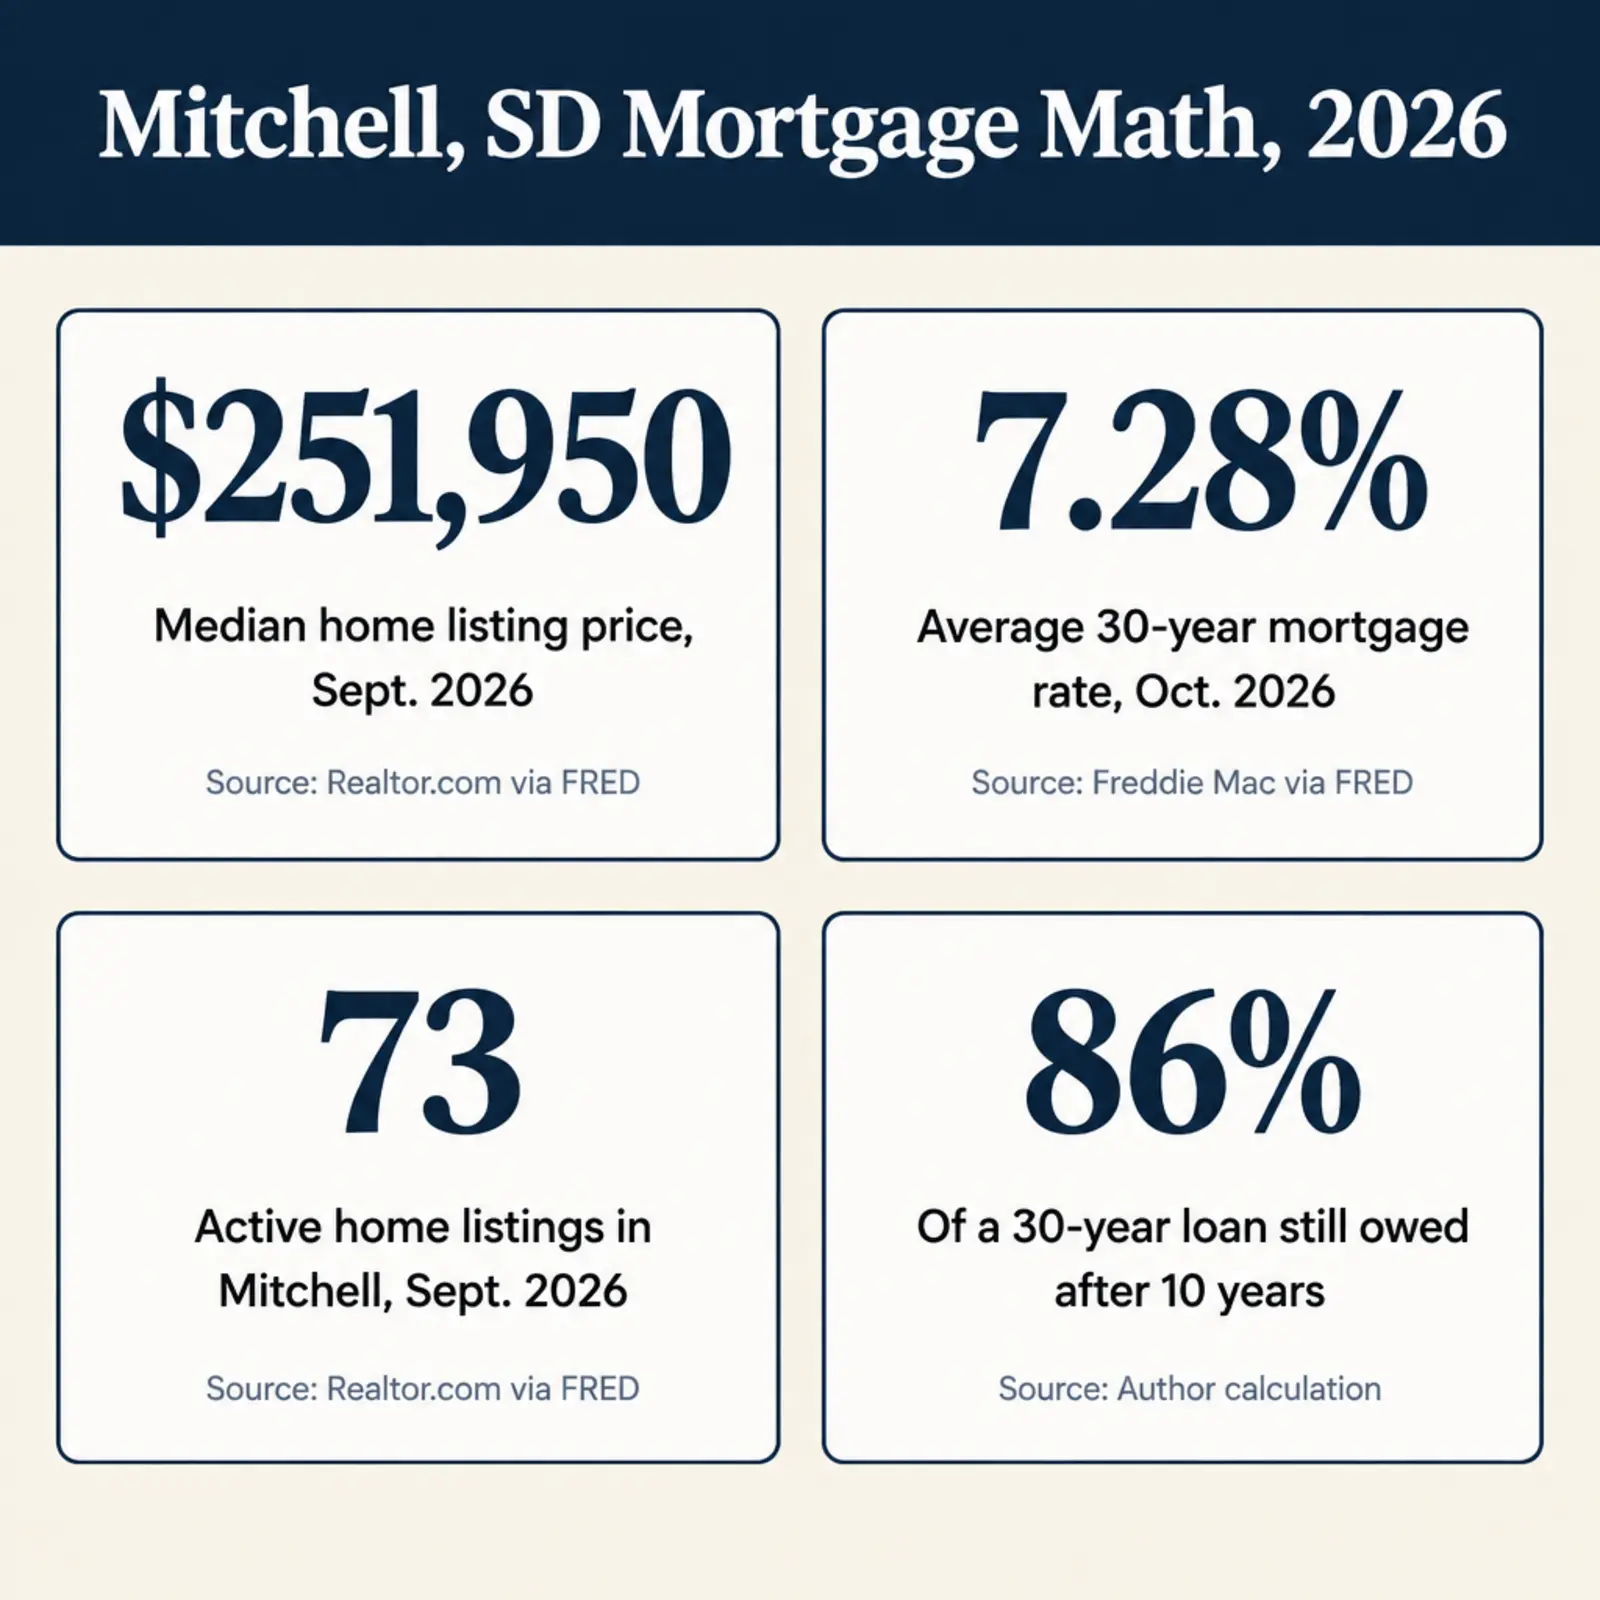
$251,950
Mitchell median home listing price, September 2026, per Realtor.com via FRED
7.28%
Average 30-year fixed mortgage rate, week of Oct. 1, 2026, Freddie Mac via FRED
73
Active home listings across the entire Mitchell market, September 2026, FRED
86%
of an illustrative Mitchell-priced loan still owed after 10 years, author's amortization calculation
Mitchell’s 2026 housing picture: a small market that swings hard
It would be simpler to describe one clean trend line for Mitchell home prices in 2026. The honest picture is a market small enough that a handful of closings move the median noticeably from month to month, which matters directly for anyone trying to size coverage off “what houses cost here.”
Mitchell, SD median home listing price, April–September 2026
Realtor.com median listing price data for the Mitchell, SD core-based statistical area, hosted by the Federal Reserve Bank of St. Louis (FRED), series MEDLISPRI33580. April through August 2026 shown; September 2026 value was $251,950.
That $97,500 swing between May’s high and August’s low, in the same market, five months apart, is not a sign the “real” value of Mitchell homes changed that much. Realtor.com counted only 73 active listings across the entire Mitchell CBSA in September 2026, per FRED. With that few homes on the market at any given time, a month where several higher-priced properties close looks very different from a month where several starter homes close, even if nothing about the underlying market actually shifted. Mitchell’s year-over-year listing price was down 21.3% as of September 2026, according to the same FRED series, a figure driven at least partly by that small-sample volatility rather than a clean, steady decline.
| Measure | Value | Source |
|---|---|---|
| Mitchell, SD median listing price | $251,950 | Realtor.com via FRED, Sept. 2026 |
| Rapid City, SD median listing price | $417,450 | Realtor.com via FRED, Sept. 2026 |
| South Dakota statewide house price index, year-over-year | +2.2% | FHFA via FRED, Q2 2026 vs. Q2 2025 |
Listing price and a repeat-sales price index measure different things. The statewide index, built from actual sales over a longer window, is a steadier read than any single month's local listing price.
The statewide number is the one worth leaning on for a sense of direction: the Federal Housing Finance Agency’s All-Transactions House Price Index for South Dakota rose from 628.65 in the second quarter of 2025 to 642.50 in the second quarter of 2026, a 2.2% year-over-year increase, according to data hosted by FRED. That index is built from actual recorded sales and mortgage data over a longer window, which makes it a far steadier measure of underlying trend than Mitchell’s own month-to-month listing price. If you are pricing your own coverage, the practical lesson is this: pull Mitchell’s current listing price yourself before you use it, since a number from even a few months ago may already be stale in a market this thin, and lean on the steadier statewide trend rather than any single month’s swing when you want a sense of direction rather than a precise local figure.
How to work it out yourself
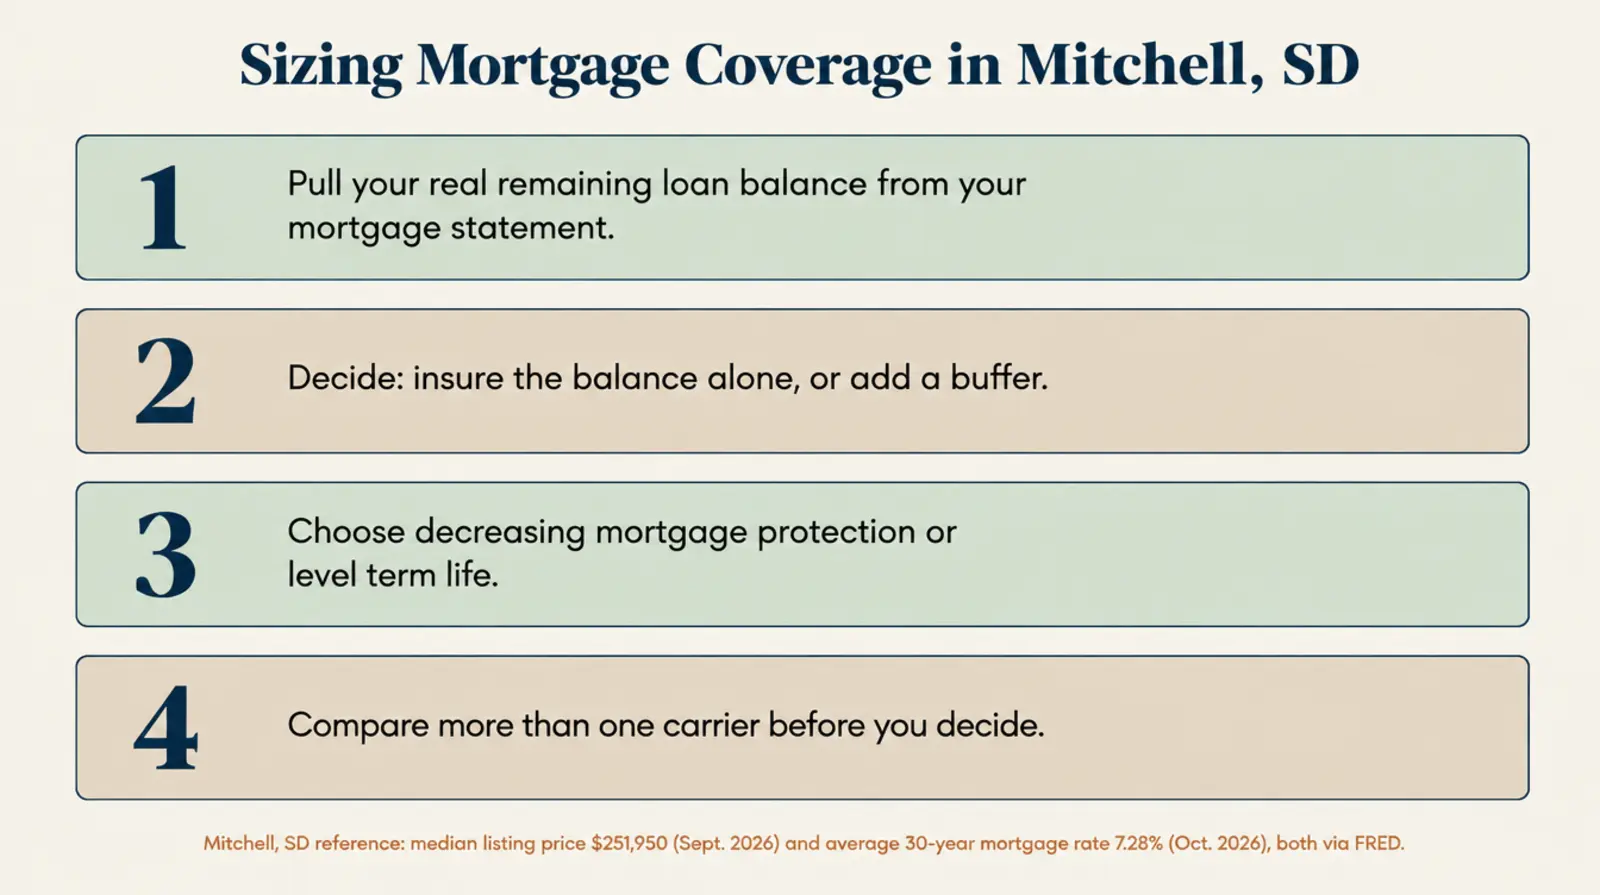
You do not need anyone else’s help to get most of the way through this math. Here is the method, step by step.
- Pull your actual remaining balance, not your original loan amount and not your home’s current value. Your latest mortgage statement has the exact figure. If you do not have a recent statement handy, most loan servicers show it online, or you can estimate it with a standard amortization calculator using your original loan amount, interest rate, and start date.
- Decide whether you are insuring the balance alone or adding a buffer. Some households insure exactly the payoff amount. Others add a cushion for closing costs on a future sale, a few months of income replacement while the family adjusts, or a rate high enough that refinancing later could increase what is owed. There is no single right answer; the point is to decide on purpose rather than by accident.
- Check whether your loan is fixed or adjustable, and where you are in the amortization schedule. As the table above shows, a fixed-rate loan pays down slowly early on. If you are within the first ten to twelve years of a 30-year loan, assume your balance is still close to your original loan amount unless you have made extra principal payments.
- Decide between decreasing-benefit mortgage protection insurance and level term life insurance. MPI tracks a declining balance automatically, which can fit a straightforward “cover the house” goal. Level term life keeps a fixed benefit and lets your beneficiary decide how to use it, which fits a broader goal that includes income replacement, other debts, or future needs beyond the mortgage. Our mortgage protection vs. term life comparison walks through that tradeoff in more depth.
- Compare more than one carrier before you decide. Underwriting classes, pricing, and product availability differ by company. What one insurer offers a given applicant in Mitchell is not necessarily what another will offer for the identical application.
You can do steps 1 through 4 yourself, today
Pulling your balance, deciding on a buffer, checking your amortization stage, and picking between decreasing or level coverage are all things you can work out with your own mortgage statement and an amortization calculator. Where a second opinion tends to help most is step 5, comparing what different carriers actually offer for your specific application, since that is the part no single company's website shows you.
You can also run these numbers yourself in about twenty minutes using our life insurance needs calculator, which walks through your mortgage balance alongside income replacement and other obligations rather than the mortgage in isolation.
Mortgage protection insurance vs. term life, briefly
Both products can address a Mitchell mortgage, but they are built differently, and the choice matters more than most people assume when they buy the first thing a lender’s mailer offers them.
Built to track your loan, and only your loan
- Death benefit typically decreases, following your original amortization schedule
- Often structured around the mortgage specifically
- Simple "cover the house" goal, nothing more
Best fitHouseholds who want coverage that tracks the loan and nothing else
A fixed benefit your beneficiary can use for anything
- Death benefit stays fixed for the full policy term
- Any named beneficiary, usable for the mortgage, income, or other debts
- Fits a broader goal beyond the house alone
Best fitHouseholds who want flexibility for income replacement or other debts too
A mortgage protection policy sized to your loan the day you closed does not know you refinanced, paid extra principal, or bought a bigger house since. Check the number against what you actually owe today, not the day you signed.
Mike Moore, Life Insurance AdvisorIf you would rather have someone local run the comparison across carriers than call companies one by one, that is what we do: Compare My Options.
Your rights during the first ten days
South Dakota law gives you a real, enforceable window to change your mind after a policy arrives. Under South Dakota Codified Law 58-15-8.1, every individual life insurance policy delivered in the state must include a notice that you can return it, in writing, within ten days of actually receiving it, and get your premium back, with the policy treated as if it had never been issued. That applies whether you bought decreasing-term mortgage protection insurance or a standalone level term policy. It is worth reading the actual policy document during that window, not just the sales materials, since the fine print is what a claim will eventually be paid against.
How we help
We are independent, so we are not built around one company’s mortgage protection product. We start with your actual remaining balance, your amortization stage, and whether decreasing or level coverage fits your household better, then compare how different carriers price that specific need rather than defaulting to whichever product a lender’s marketing mailer pushed first. Serving all of South Dakota, including Davison County and Mitchell, means the local housing numbers above are not an abstraction to us; they are the starting point for the conversation.
What you get
A coverage amount sized to your real loan balance, not a guess based on your original mortgage or your home’s peak listing price from a volatile month. A clear answer on whether decreasing-benefit mortgage protection or level term life fits your goals better. And a comparison across more than one carrier, since that variation is the part hardest to see without asking.
Size your Mitchell mortgage coverage with real numbers
Bring your mortgage statement, or your best estimate of your remaining balance, and we will walk through decreasing-term and level term options side by side.
Not ready to talk to anyone yet? Read How It Works first and come back when you are. If you want to work through the underwriting side before the sizing question, our guide to mortgage protection insurance vs. term life insurance is a good next stop.
Frequently asked questions
How much mortgage protection insurance do I need in Mitchell, SD?
Start with your actual remaining loan balance, not your original loan amount or your home’s current value. Pull your latest mortgage statement for the exact figure, or estimate it with an amortization calculator using your original loan amount, rate, and start date. If you bought near Mitchell’s September 2026 median listing price of $251,950, per Realtor.com data hosted by FRED, and financed most of it, your balance is still close to the original loan for the first several years, because fixed-rate loans pay down slowly at first. Some homeowners add a buffer for closing costs or a short income-replacement window on top of the bare balance; others insure the balance alone. Either is defensible. What matters is starting from your real number, not a guess.
What is the difference between mortgage protection insurance and term life insurance?
Mortgage protection insurance (MPI) is typically a decreasing-benefit policy sized to your original loan and its amortization schedule, and many MPI policies are structured so proceeds address the mortgage specifically. A standalone level term life policy pays a fixed death benefit to whatever beneficiary you name, usually your spouse or family, who can use the money for the mortgage, for lost income, or for anything else. For a full side-by-side comparison of features, underwriting, and typical costs, see our guide to mortgage protection insurance versus term life.
Why did Mitchell’s home prices swing so much in 2026?
Because Mitchell is a small housing market. Realtor.com counted just 73 active listings in the entire Mitchell, SD core-based statistical area in September 2026, according to data hosted by FRED. When a market that small sells a handful of higher-priced or lower-priced homes in a given month, the median listing price can swing by tens of thousands of dollars without reflecting any real shift in what a typical house is worth. A single month’s figure is more volatile here than in a larger city like Rapid City or Sioux Falls, which is exactly why it’s worth checking the current number yourself rather than relying on a figure from an old article.
Do I need mortgage protection insurance if I already have life insurance through my job?
Group life insurance through an employer is usually one to two times your salary and ends the day you leave that job, whether you choose to leave or are let go. If your mortgage balance is close to or larger than that group benefit, or if you are not certain your job is permanent, that gap is worth sizing separately from your mortgage math. Our guide on whether employer life insurance is enough walks through that comparison in more detail.
Can I get mortgage protection insurance without a medical exam in South Dakota?
No-exam and simplified-issue products exist as a category in today’s market and are worth asking about directly with a licensed agent, since eligibility, underwriting requirements, and cost depend on your age, health, and the specific carrier and product. We are not able to state that any particular no-exam outcome or timeline is available to a given applicant in advance of underwriting.
What happens to my mortgage in South Dakota if I die and there is no coverage?
If you have a co-borrower, such as a spouse, they typically remain responsible for the full loan under the terms you both signed. If you are the sole borrower, the loan does not disappear. It becomes a debt of your estate, and under federal law, 12 U.S.C. Section 1701j-3(d)(5), a lender cannot invoke a due-on-sale clause to force immediate repayment or foreclosure when a home passes to a relative through inheritance; the Consumer Financial Protection Bureau has directed mortgage servicers to have procedures in place for allowing heirs to continue paying the mortgage. That protects the right to keep the house. It does not supply the money to do it. Whoever inherits the mortgage still needs income, savings, or insurance proceeds to make the payment every month.
Can I cancel a mortgage protection or life insurance policy after I buy it?
Yes. South Dakota law (SDCL 58-15-8.1) requires every individual life insurance policy delivered in the state to include a free-look provision: you can return the policy in writing within ten days of receiving it and get your premium back, with the policy treated as if it had never been issued. After that window, you can generally still cancel by stopping payment, though you will not get past premiums refunded, so it is worth reading the policy carefully during those first ten days.
Before you decide
This article is general education, not insurance, legal, financial, or tax advice. Product availability, underwriting outcomes, rate classes, and premiums vary by carrier and are subject to underwriting. No coverage exists until a policy is issued and in force. Any guarantees are subject to the claims-paying ability of the issuing insurer. The worked examples in this guide are hypothetical and illustrative only, not a quote or a promise of any specific coverage amount, premium, or underwriting outcome. Please review actual policy documents and speak with a licensed agent about your situation.
Sources
- Federal Reserve Bank of St. Louis (FRED) — Housing Inventory: Median Listing Price in Mitchell, SD (CBSA) (MEDLISPRI33580) — $251,950 in September 2026, and $307,850 to $222,500 for April through August 2026; underlying data from Realtor.com
- Federal Reserve Bank of St. Louis (FRED) — Housing Inventory: Median Listing Price Year-Over-Year in Mitchell, SD (CBSA) (MEDLISPRIYY33580) — negative 21.26% year-over-year change as of September 2026; underlying data from Realtor.com
- Federal Reserve Bank of St. Louis (FRED) — Housing Inventory: Active Listing Count in Mitchell, SD (CBSA) (ACTLISCOU33580) — 73 active listings in September 2026; underlying data from Realtor.com
- Federal Reserve Bank of St. Louis (FRED) — Housing Inventory: Median Listing Price in Rapid City, SD (CBSA) (MEDLISPRI39660) — $417,450 in September 2026; underlying data from Realtor.com
- Federal Reserve Bank of St. Louis (FRED) — 30-Year Fixed Rate Mortgage Average in the United States (MORTGAGE30US) — 7.28% for the week of October 1, 2026; underlying data from Freddie Mac’s Primary Mortgage Market Survey
- Federal Reserve Bank of St. Louis (FRED) — 15-Year Fixed Rate Mortgage Average in the United States (MORTGAGE15US) — 6.60% for the week of October 1, 2026; underlying data from Freddie Mac’s Primary Mortgage Market Survey
- Federal Reserve Bank of St. Louis (FRED) — All-Transactions House Price Index for South Dakota (SDSTHPI) — index value 642.50 for Q2 2026, up from 628.65 in Q2 2025, a 2.2% year-over-year increase; data produced by the Federal Housing Finance Agency
- U.S. Census Bureau — Population and Housing Unit Estimates, Vintage 2024 (sub-county totals, South Dakota) — Mitchell city population estimate of 15,621 as of July 1, 2024
- U.S. Census Bureau — American Community Survey 2020-2024 5-Year Estimates, Mitchell city, Davison County, SD — population 15,649; median household income $58,620 (±$7,441); median value of owner-occupied housing units $192,200 (±$16,138)
- LIMRA — “92 Million Reasons to Talk About Life Insurance,” 2026 Insurance Barometer Study — 38% of American adults, about 92 million people, say they need life insurance or need more of it
- Consumer Financial Protection Bureau — CFPB Clarifies Mortgage Lending Rules to Assist Surviving Family Members — servicer procedures for allowing heirs/successors in interest to continue paying a mortgage after a borrower’s death
- Cornell Law School, Legal Information Institute — 12 U.S. Code Section 1701j-3 — due-on-sale clause exception at subsection (d)(5) for a transfer to a relative resulting from the death of a borrower
- South Dakota Legislature — SDCL 58-15-8.1 — accessed October 2026; ten-day free-look cancellation provision for individual life insurance policies delivered in South Dakota
Related reading: Mortgage Protection Insurance vs. Term Life: Which Is Better?, Mortgage Protection Insurance in Rapid City, 2026, Is Your Employer’s Life Insurance Enough? A 2026 SD Guide, and 10 vs 20 vs 30 Year Term Life: Which Length Should You Buy?. See current options for mortgage protection insurance, or learn more about who we help.